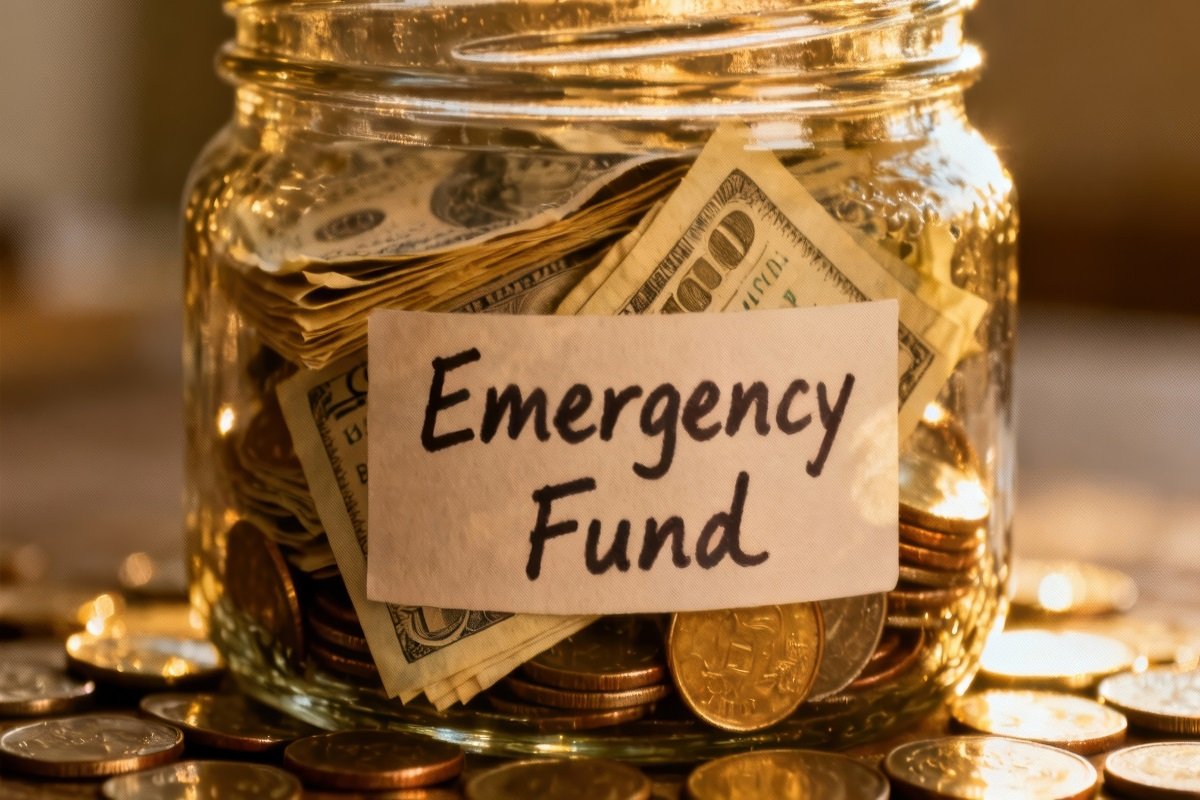
Maybe you’ve opened your banking app more times than you want to admit. You look at the balance. You know you should be saving. You want to save. But somehow the month ends before there’s anything left, the next paycheck arrives, and the cycle starts again.
There’s nothing embarrassing about that. Life is expensive, bills don’t wait, and sometimes your income simply doesn’t leave much room. The answer isn’t to blame yourself — it’s to create a small amount of space, then protect that space.
This guide will walk you through building an emergency fund starting from exactly where you are, even if that’s $0.
Table of Contents
- Your First Goal Is Not $10,000
- Why Your First $100 Matters
- An Emergency Fund Is More Than Money
- Find Your Real Number, Not Someone Else’s
- How to Actually Build the Habit
- Where to Keep Your Emergency Fund
- What Actually Counts as an Emergency
- Turning $100 Into $1,000
- If You Have Debt or Irregular Income
- Your Personal Safety Number
- Using and Rebuilding Your Fund
- Your Starting-From-$0 Action Plan
- Emergency Fund FAQs
1. Your First Goal Is Not $10,000
This is where I want you to change the way you think about emergency savings.
Don’t start by thinking:
“I need six months of expenses.”
Start with:
“I want my first $100.”
That’s it.
Your first $100.
Once you reach it, aim for $250.
Then $500.
Then $1,000.
After that, you can work toward a larger emergency fund based on your household expenses and financial situation.
Big goals become less frightening when you break them into smaller milestones.
You don’t need to climb the entire staircase today.
You only need to take the next step.
2. Why Your First $100 Matters
Imagine you have $0 in savings.
Your car suddenly needs a $100 repair.
You have two choices.
You could put the expense on a credit card.
You could borrow the money.
Or, if you had already built that first $100, you could use money you deliberately saved for unexpected situations.
The repair still hurts.
But the financial damage can be different.
That is what an emergency fund gives you.
A little breathing room.
A little flexibility.
A little more control.
3. An Emergency Fund Is More Than Money
This is something financial articles don’t always explain.
An emergency fund can change how you feel.
When you have nothing saved, a surprise expense can immediately trigger fear.
You start calculating.
“How am I going to pay this?”
“Who can I borrow from?”
“Can I put this on my credit card?”
“What bill can I delay?”
Having savings doesn’t mean emergencies stop happening.
It means you have something between yourself and the emergency.
Even a small amount can change that feeling.
You are no longer completely unprepared.
4. Find Your Real Number, Not Someone Else’s
You may see someone online saying:
“Save 20% of your income.”
That might work for them.
It may not work for you.
Maybe your rent is high.
Maybe you support your family.
Maybe you’re paying off debt.
Maybe childcare costs are significant.
Maybe your income changes every month.
Maybe you’re already cutting expenses as much as you reasonably can.
Your emergency fund needs to fit your actual life.
So don’t copy someone else’s number.
Find your number.
Sit down with your money
Take 30 minutes.
No television.
No social media.
No distractions.
Open your bank account.
Look at your recent transactions.
Then write down your monthly income.
Next, list your essential expenses.
Housing.
Utilities.
Food.
Transportation.
Insurance.
Debt payments.
Childcare.
Other necessary expenses.
Then look at everything else.
Restaurants.
Shopping.
Subscriptions.
Entertainment.
Hobbies.
Online purchases.
You are not doing this to criticize yourself.
You’re doing it because you can’t change what you don’t understand.
Find your financial breathing room
Now ask yourself:
“Where can I create $25?”
Don’t look for $1,000.
Look for $25.
Maybe you discover a subscription you forgot about.
Maybe you realize you’re spending more on delivery than you thought.
Maybe you can reduce one shopping habit.
Maybe you can redirect a small amount from every paycheck.
Maybe you can earn an extra $25 occasionally.
Your first goal is to create breathing room.
That breathing room becomes your savings.
5. How to Actually Build the Habit
Try the $10 rule
If money is extremely tight, start with $10.
Put $10 into a separate savings account.
Don’t laugh at it.
Don’t tell yourself it’s too small to matter.
You are changing a habit.
Next payday, put another $10 away.
Then another.
Ten deposits of $10 become $100.
You have now built something that didn’t exist before.
And more importantly, you’ve proved something to yourself.
You can save.
What if you save $25 a week?
Let’s make this practical.
If you put aside $25 each week, you would contribute about $100 per month.
Over a year, that is approximately $1,300, before considering any interest.
If $25 a week is too much, reduce it.
If you can save more, increase it.
The number isn’t the point.
The habit is.
Your emergency fund should grow at a pace your budget can handle.
Make Saving Automatic
Here’s a simple change that can make saving easier.
Don’t wait until the end of the month to see what’s left.
By then, there may be nothing left.
Instead, if your finances allow it, arrange an automatic transfer shortly after you receive your income.
It could be:
$10.
$25.
$50.
$100.
Whatever amount is realistic.
You don’t need to remember.
You don’t need to make the decision every week.
The money moves automatically.
Over time, saving becomes part of your routine.
Make Saving Automatic
Here’s a simple change that can make saving easier.
Don’t wait until the end of the month to see what’s left.
By then, there may be nothing left.
Instead, if your finances allow it, arrange an automatic transfer shortly after you receive your income.
It could be:
$10.
$25.
$50.
$100.
Whatever amount is realistic.
You don’t need to remember.
You don’t need to make the decision every week.
The money moves automatically.
Over time, saving becomes part of your routine.
6. Where to Keep Your Emergency Fund
There is a psychological difference between seeing $500 in your everyday checking account and seeing $500 in a separate savings account labelled for emergencies.
The first can feel like spending money.
The second feels like protected money.
Consider keeping your emergency savings in a separate savings account that is accessible when you genuinely need it.
You want the money available.
But you don’t want it sitting in the same place where you buy groceries, order dinner, or shop online.
Make the right decision easier.
Don’t invest your emergency fund
Your emergency fund has a different job from your long-term investments.
You want your emergency savings to be available when you need it.
Investments can rise and fall in value.
If an emergency happens during a market decline, you don’t want to be forced to sell investments at an inconvenient time simply because you need cash.
For emergency savings, accessibility and stability generally matter more than chasing higher returns.
Your investments can have a different purpose.
7. What Actually Counts as an Emergency
A useful way to decide is to ask three questions: Was it unexpected? Is it necessary? Does it need to be dealt with now? If the answer to all three is yes, using your emergency fund may make sense.
| Usually an Emergency | Usually Not an Emergency |
|---|---|
| Car breaks down and you need it for work | A new TV because yours is outdated |
| Essential home repair (heating, plumbing, roof leak) | A planned holiday or vacation |
| Unexpected necessary medical expense | A new phone because a newer model released |
| Sudden loss of income | A sale on something you’ve wanted |
| Urgent appliance replacement | A predictable annual expense (birthday, insurance renewal) |
If you’re still unsure, ask: “If I don’t spend this money today, what happens?” If the answer is that you simply won’t get something you want, it’s probably not an emergency. If your safety, housing, or ability to work is affected, the situation may be different.
8. Turning $100 Into $1,000
Break $400 into weekly chunks
Say you’ve reached $100 and need another $400 to hit $500. Spread over four months, that’s $100 a month — about $25 a week. Now the goal feels manageable: you’re not looking for $400 today, just $25 this week.
Look for five $20 opportunities
Instead of asking “how do I save $400?” ask “where can I find five $20 savings opportunities?” Less takeaway, a canceled subscription, better grocery planning, or an extra $20 from your paycheck — do that four times and you’ve created $400.
Use a “pause list”
When you want something non-essential, don’t buy it immediately. Write down what you want, the price, and the date. Wait a few days, then look again. Some things will still matter; others won’t. That gap can save you money.
Sell things you no longer use
Old electronics, clothes, furniture, or equipment sitting unused can become an initial boost to your fund. Selling $200 worth of items can be significant progress toward your first milestone.
Use windfalls intentionally
A tax refund, bonus, or gift is a chance to make a decision before the money disappears. You might split it — for example 50% to savings, 25% to debt, 25% for something you enjoy.
9. If You Have Debt or Irregular Income
“I have credit card debt — how can I save?”
High-interest debt deserves serious attention, but having zero emergency savings can leave you vulnerable to taking on even more debt when something unexpected happens. Some people choose to build a small starter cushion first, then focus aggressively on high-interest debt, and redirect more toward savings once that debt is under control.
If your income changes month to month
Build your plan around a conservative baseline month, then direct extra toward savings in stronger months. For example: normal month, save $50; strong month, save $150; very strong month, save $250.
If you’re living paycheck to paycheck
Your strategy may need two parts: reduce unnecessary expenses where realistically possible, and look for ways to increase income. Don’t punish yourself for failing to save money that simply isn’t available — start smaller and work on the income side too.
10. Your Personal Safety Number
There isn’t one emergency-fund number that works for everyone. Instead, calculate your essential monthly expenses and use that as your baseline.
| Essential Expense | Example Monthly Cost |
|---|---|
| Housing | $1,500 |
| Utilities | $250 |
| Food | $500 |
| Transportation | $300 |
| Insurance | $250 |
| Minimum debt payments | $200 |
| Total essential expenses | $3,000 |
Using this example: one month of expenses = $3,000, three months = $9,000, six months = $18,000. These numbers can look intimidating — that’s fine. You don’t need to build them immediately. A realistic path looks like this:
$100 → $500 → $1,000 → one month of expenses → three months → six months if your situation calls for it.
Note: Three to six months of expenses is a useful rule of thumb, not a universal law. A single person with stable income and low fixed costs may need less; someone supporting a family with a variable income may need more.
11. Using and Rebuilding Your Fund
Using your emergency fund doesn’t mean you failed — that’s what the money is there for. Say you’ve saved $1,000 and your car needs a $700 repair. You use $700, and your balance drops to $300. That’s okay. The next step isn’t shame; it’s rebuilding.
Once the emergency has passed, look at your new balance and create a rebuilding plan. You don’t need to restore it immediately — even $25 or $50 a month restarts the habit. This cycle (build, use, rebuild) is what financial resilience actually looks like.
12. Your Starting-From-$0 Action Plan
Today:
1. Open your bank account and write down your current savings balance.
2. Review your last 30 days of spending.
3. Find one expense you can realistically reduce.
4. Choose your first target — start with $100.
5. Transfer your first small amount into savings.
6. Set up an automatic transfer if possible.
7. Keep the money separate from everyday spending, then leave it alone and let it grow.
13. Emergency Fund FAQs
How much should I have in an emergency fund?
There’s no universal amount. A common approach is to eventually cover several months of essential expenses, but your right target depends on income stability, household responsibilities, debt, and other circumstances. Start with an achievable milestone rather than worrying about the final number.
Is $1,000 enough for an emergency fund?
For many people, $1,000 is a useful milestone. It won’t cover every possible emergency, but it can protect against smaller unexpected expenses. Treat it as a milestone, not a universal rule.
Where should I keep my emergency fund?
Many people use an accessible savings account. It should offer reasonable access to your money without unnecessary fees or complexity, and it generally serves a different purpose than long-term investments.
Should I invest my emergency fund?
Emergency savings and investments serve different purposes. Because emergencies can happen at inconvenient times, many people prefer to keep emergency savings stable and accessible rather than exposed to market fluctuations.
Should I save money if I have debt?
It depends on the type and cost of the debt. High-interest debt deserves serious attention, but having no emergency savings can leave you vulnerable to taking on more debt when an unexpected expense appears. A small cushion combined with a focused repayment strategy can work for some people.
What if I have to use my entire emergency fund?
Don’t panic — you used the money for the reason you built it. Once the emergency is over, restart your savings plan. Even a small contribution begins rebuilding the fund.
How long does it take to build an emergency fund?
It depends on your income, expenses, savings rate, and target. Some people reach $1,000 quickly; others need many months. Focus on consistent progress from your own starting point rather than comparing timelines with others.
What if I can't save anything right now?
Start by understanding why. If unnecessary spending is consuming part of your income, look for one expense to reduce. If essential expenses already consume nearly everything you earn, look for realistic ways to increase income. Even if you can’t save today, you can still begin planning.
Final Thoughts
An emergency fund can’t prevent life from happening. It can’t stop a car from breaking down or guarantee your job will always be secure. But it can give you something valuable: time, options, and breathing room.
If you’re starting from $0, don’t be embarrassed and don’t compare your savings with someone else’s. Start small. Build your first $100, then work toward $500, then $1,000, then a fund that fits your life. And if you ever have to use it, remember what it was created to do — protect you. Then start rebuilding, one deposit at a time.